 Sky
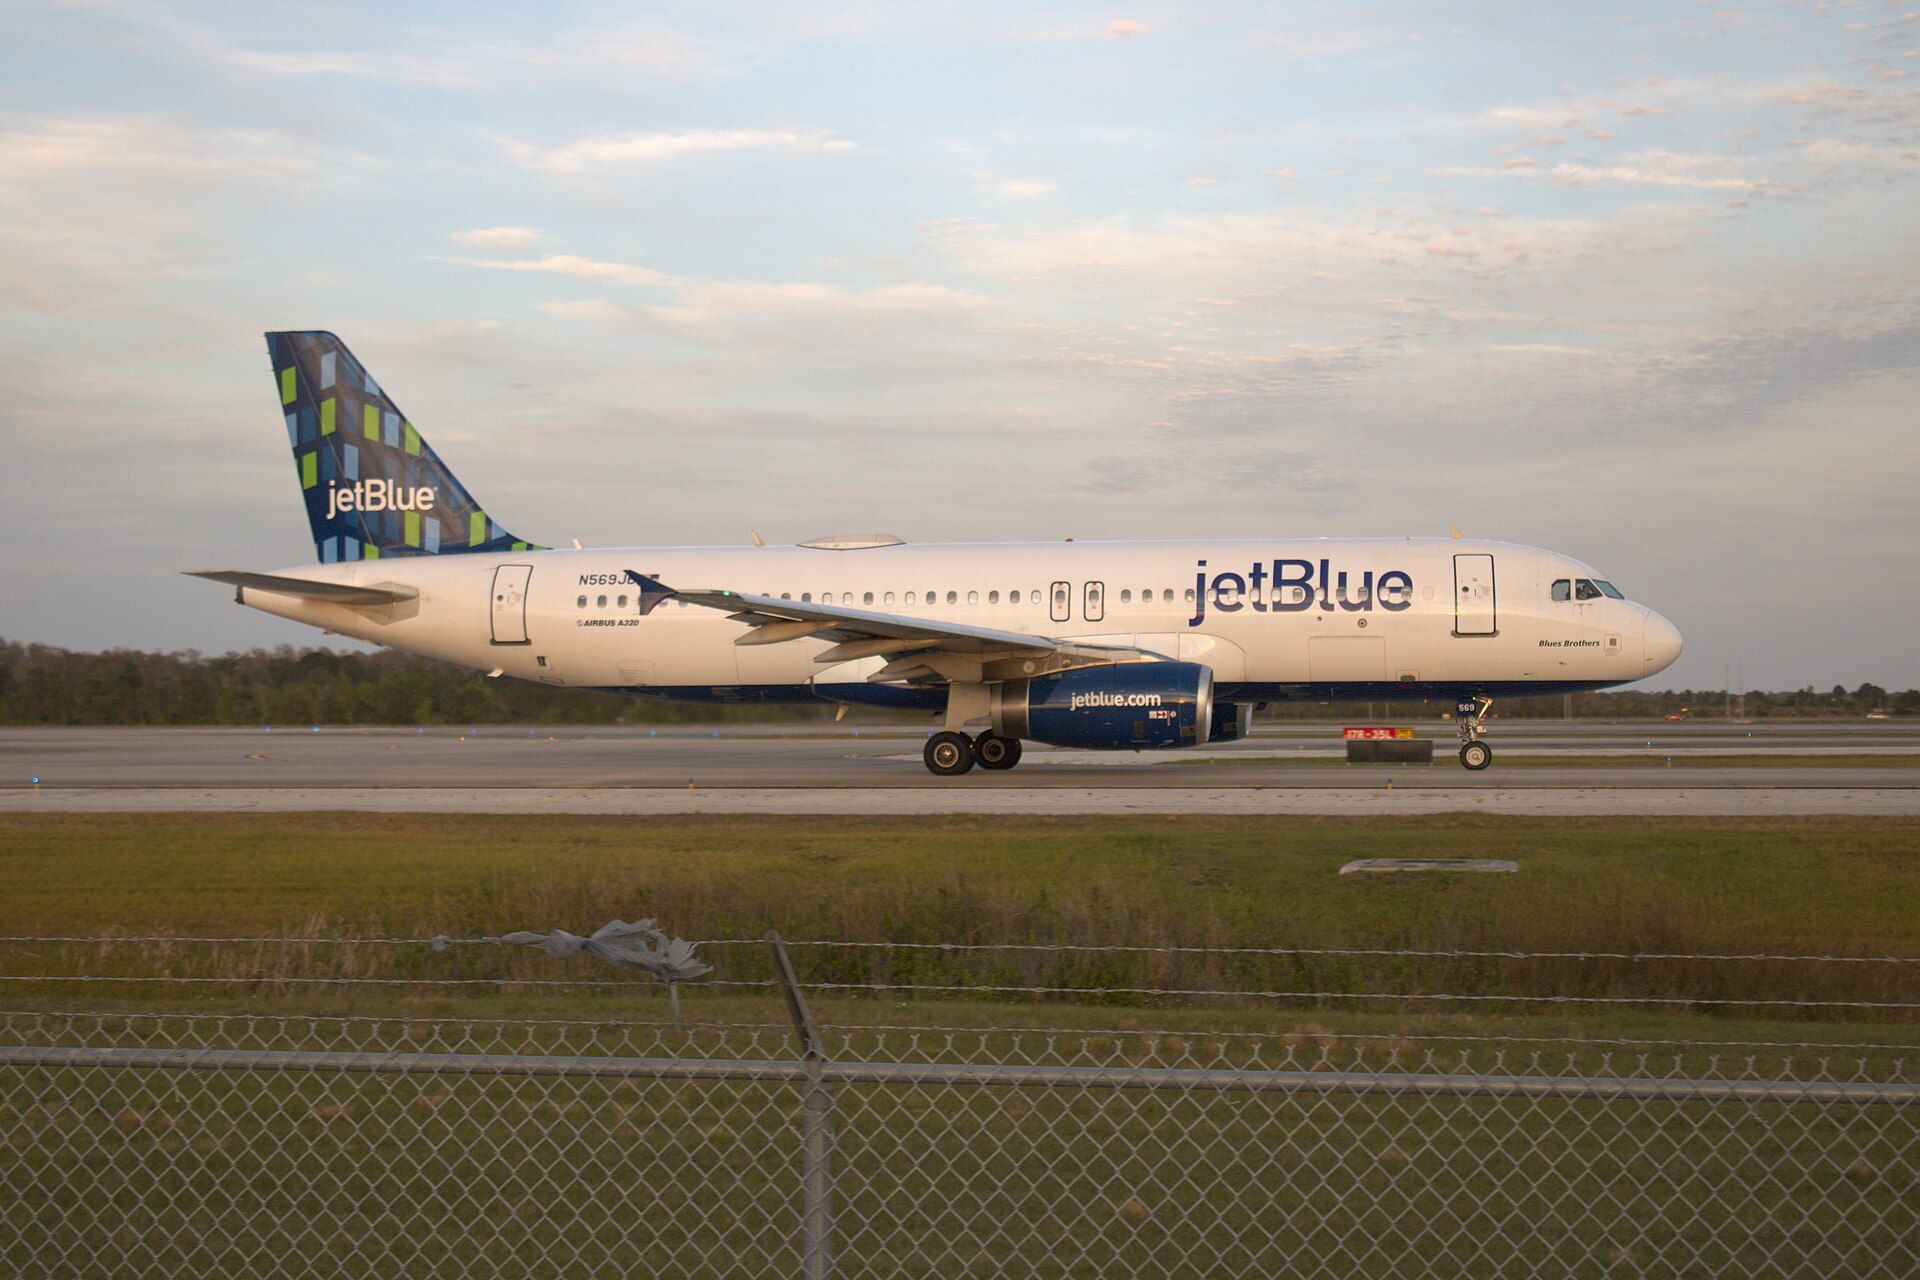
JetBlue Airways has spent the better part of two years telling investors that its turnaround plan would restore profitability and rebuild a premium leisure brand battered by engine troubles, soft domestic demand and the collapse of its proposed Spirit Airlines merger. This week, the market delivered a blunt rebuttal. Reports that the carrier's creditors have engaged restructuring advisers, combined with a share price that has slid to an all-time low, have transformed what was framed as a strategic reset into a question of financial resilience.
The development matters because creditor behavior is often the earliest public signal of how serious a liquidity situation has become. Lenders and bondholders typically tolerate losses while they believe management has a credible path back to positive cash flow. Bringing in restructuring specialists suggests that some creditors are now stress-testing scenarios in which that path narrows: a prolonged period of elevated fuel prices, weaker-than-expected corporate and leisure demand, or further disruption from the Pratt & Whitney Geared Turbofan engine inspections that have grounded a meaningful share of the airline's Airbus A220 and A320neo-family fleet. To be clear, the presence of advisers is not itself a default or a bankruptcy filing. It is, however, a hedge, and markets read hedges as a warning.
The background to this moment is a sequence of setbacks that have left JetBlue with little room for error. The carrier's attempt to acquire Spirit Airlines was blocked on antitrust grounds, removing the scale benefits management had counted on to compete with the big four US airlines. At the same time, the GTF engine issue forced aircraft out of service, driving up costs and disrupting schedules during peak periods. Domestic leisure demand, the backbone of JetBlue's network, normalized after the post-pandemic surge while costs remained stubbornly high. Management responded with a plan to cut unprofitable routes, defer aircraft deliveries, improve operational reliability and lean into premium and loyalty revenue, including its TrueBlue program and co-branded card economics. Those are sensible levers, but they take time, and time is precisely what a falling share price and anxious creditors do not generously provide.
Fuel is the immediate accelerant. Jet fuel prices are sensitive to geopolitical risk and refinery economics, and airlines have limited ability to pass through sudden spikes without suppressing demand. For a carrier with a thinner margin buffer than its larger rivals, every sustained increase in the fuel bill eats directly into the cash needed to service debt and fund the turnaround. JetBlue also carries a substantial aircraft order book and lease obligations, commitments that are difficult to renegotiate quickly and that weigh on the balance sheet precisely when flexibility is most valuable.
The industry implications extend beyond one airline. JetBlue has long positioned itself as the most credible challenger to the US mega-carriers, a low-cost, high-service operator that pushed the majors on product and price in markets such as New York, Boston and Fort Lauderdale. If its restructuring becomes formal, the competitive dynamic shifts: the big four would face less pressure on certain routes, and consumers could see reduced choice and firmer fares in the very markets where JetBlue has been a disruptive force. Airport authorities and suppliers in its focus cities would also feel the effects of any capacity cuts. For the broader sector, the episode reinforces a lesson from previous cycles: in a high-cost environment, scale and a strong balance sheet are decisive, and mid-sized carriers without either face a structural disadvantage.
There is also a labor dimension. Pilot and crew contracts negotiated during better times set fixed cost floors, and any restructuring conversation will inevitably touch on productivity and work rules. That makes the path forward politically and operationally complicated, particularly with unions that have already made concessions during past downturns.
Looking ahead, the key indicators to watch are liquidity disclosures, covenant headroom, the pace of engine-related groundings and any signals of asset sales or sale-leaseback transactions. Management will likely emphasize that restructuring advisers are being engaged by creditors, not the company, and that operations continue normally. That may be true, but the market has already begun pricing in a wider range of outcomes. JetBlue's turnaround is not yet lost, but it is now being underwritten by parties whose patience is measured in quarters, not years. The next few earnings cycles will determine whether this is a turbulent chapter in a recovery or the opening of a much harder story.
Comments (0)
No comments yet. Be the first to share your thoughts.